Home Depot Is Down 24% From Its High. Here's Why I'd Hold It for a Decade.
Home Depot's stock has underperformed the S&P 500 over the last five years, largely due to a frozen housing market. Despite this, the author advocates holding the blue-chip stock for the next decade.
Intelligence analysis by Gemini 2.5 Flash
The article presents a bullish long-term case for Home Depot, highlighting its strong competitive advantages, solid industry leadership, and the expectation of an eventual housing market rebound. It argues that the company's robust profit generation and strategic focus on professional contractors position it for future outperformance.
Imagine Home Depot as a giant store full of everything grown-ups need to fix up their houses, like big pieces of wood, paint, and tools. Right now, not many people are buying or selling houses because it's a bit tricky with prices and loans. This means Home Depot isn't selling as much as usual, so its stock price has gone down a bit. But there aren't enough houses for everyone, so eventually, more people will start buying and fixing homes. When that happens, Home Depot will be super busy again, like a busy beehive, and its stock will likely go back up because it's really good at what it does and has lots of loyal customers, especially builders.
Analysis
Home Depot, a pioneer in big-box home improvement retail, has faced significant headwinds in recent years, with its stock down 11% over the last five years, underperforming the broader S&P 500. This downturn is primarily attributed to a stagnant housing market, characterized by a 'lock-in effect' from low pandemic-era mortgage rates, high housing prices, and current elevated mortgage rates. However, the article posits that these challenges present a buying opportunity for long-term investors, asserting that the company's fundamental strengths and market position make it a compelling hold for the next decade.
Competitive Advantages
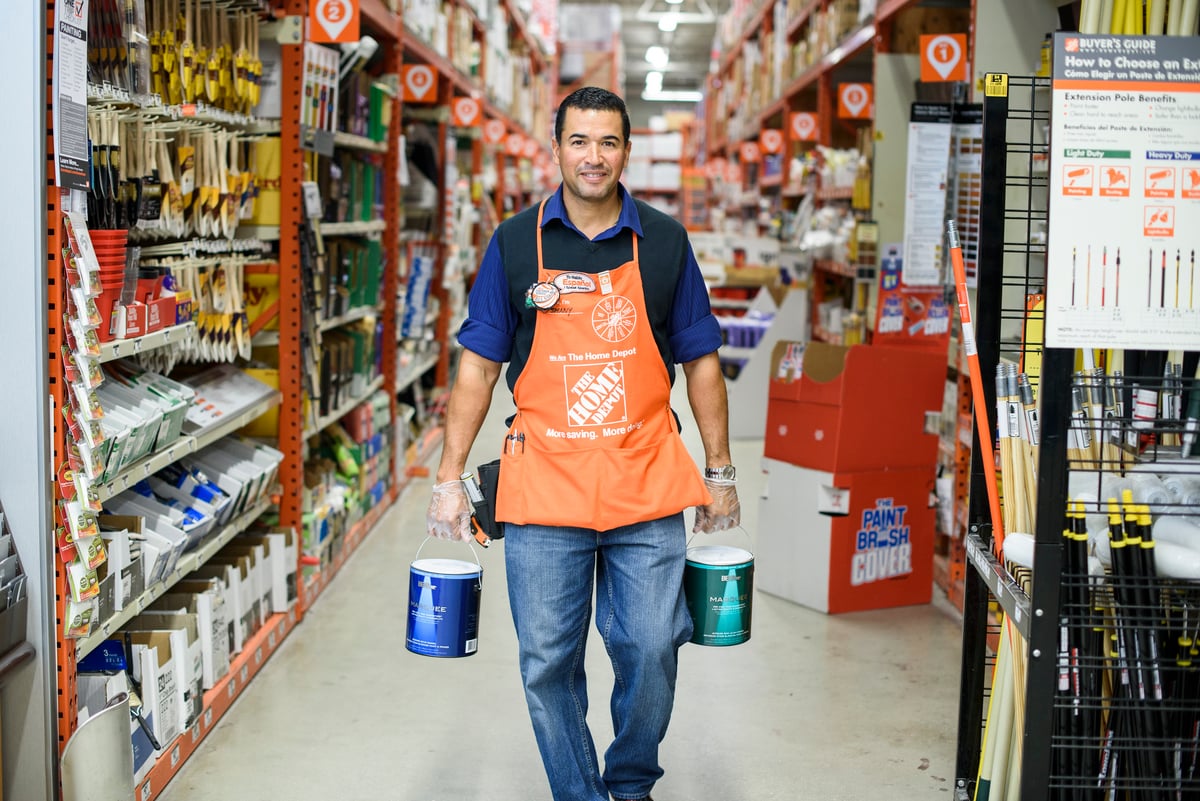
Home Depot operates within a duopoly alongside Lowe's, commanding significant market share in the fragmented home improvement industry. The company's unmatched scale, extensive reach, advanced technology, and broad product range create substantial barriers to entry for competitors. A key differentiator for Home Depot is its strategic focus on the professional contractor segment, which it views as its primary growth driver. This commitment is evidenced by its acquisition of SRS Distribution, a building materials distribution company, aimed at bolstering its services to professional clients.
Furthermore, Home Depot has made substantial investments in omnichannel capabilities, enhancing customer convenience through its app for delivery and in-store pickup options. The company also offers digital project-planning tools, which further integrate its services into the customer's project lifecycle, from conception to completion. These technological and strategic investments solidify its competitive moat, making it difficult for pure-play e-commerce companies like Amazon to disrupt its market share, especially given the bulky nature of many of its products.
4 Million Homes
The primary drag on Home Depot's recent performance has been the housing market, which has been largely frozen since the end of the pandemic. The confluence of factors—low existing mortgage rates discouraging sales, high housing prices, and currently high interest rates—has stifled transactions and, consequently, demand for home improvement projects associated with new homeownership. Despite these immediate challenges, the article highlights a critical underlying factor: an estimated shortage of approximately 4 million homes in the country.
This significant housing deficit suggests that a rebound is inevitable, whether driven by lower interest rates or policy initiatives. When the housing market eventually thaws and activity increases, Home Depot is exceptionally well-positioned to capitalize on the renewed demand for building materials and home improvement supplies. The company's extensive store network and established supply chains will enable it to readily serve both new homeowners and those undertaking renovations, translating directly into increased sales and profitability. The long-term demographic trends and the structural undersupply of housing underpin the optimistic outlook for a market recovery.
12.5% Operating Margin
Home Depot is characterized as a robust profit machine, distinguishing itself from many brick-and-mortar retailers that rely on high volumes and thin margins. The company consistently achieves high volumes coupled with healthy profit margins. In its most recent earnings report, Home Depot projected an operating margin of 12.5%, a figure that historically has been closer to 15% in a healthier housing market. This indicates significant potential for margin expansion once market conditions improve, allowing the company to revert to its historical profitability levels.
Beyond its operating margins, Home Depot demonstrates strong financial health through other metrics, such as a return on invested capital (ROIC) of 25.7% in 2025. This high ROIC signifies efficient capital allocation and a strong ability to generate profits from its investments. The company's commitment to returning value to shareholders through share buybacks and dividends, combined with its inherent growth potential tied to the housing market's eventual recovery, positions it as a compelling investment. The article concludes that with an anticipated rebound in the housing sector, Home Depot is poised to resume its historical trend of outperforming the stock market over the coming decade.
Key points
- Home Depot's stock is down 11% over the last five years, underperforming the S&P 500.
- The company benefits from a duopoly in home improvement retail, with unmatched scale and product range.
- A key growth strategy is its focus on professional contractors, supported by acquisitions like SRS Distribution.
- The housing market has been 'frozen' since the pandemic, but an estimated shortage of 4 million homes suggests an eventual rebound.
- Home Depot is a 'profit machine' with a projected 12.5% operating margin and a 25.7% return on invested capital in 2025.
Should the housing market rebound as anticipated, driven by lower interest rates or policy changes, Home Depot is exceptionally well-positioned to benefit from increased demand for home improvement products. Its strong market position and focus on professional contractors could lead to significant revenue growth and a return to higher operating margins, rewarding long-term investors.
A prolonged stagnation in the housing market, potentially due to persistently high interest rates or a deeper economic downturn, could continue to suppress Home Depot's growth. This scenario would delay the anticipated rebound, impacting the company's profitability and stock performance over the medium term.
Market signals
- HD The article argues Home Depot is a long-term hold due to its competitive advantages, industry leadership, and anticipated housing market rebound.
AI-generated analysis of potential market relevance. Not financial advice.