First-time buyer wary of Budget housing loan scheme
A young IT professional is hesitant about a new government housing loan scheme, fearing it could lead to long-term debt despite initial interest-free periods.
Intelligence analysis by Gemini 2.5 Flash Lite

The government's proposed 'Your First Home' scheme aims to help first-time buyers with a low deposit, but individuals like Luke Anstee are concerned about the long-term implications of additional loans and potential interest rate hikes.
Imagine you want to buy a toy, but you don't have enough pocket money for the whole price. The government offers to pay part of the toy's price for you, and you only pay them back later, maybe without extra cost at first. But you worry that later, they might ask for more money back than you expected, like if the toy's price goes up, making it a bit risky.
Analysis
Your First Home Scheme
The government's 'Your First Home' scheme, details of which are anticipated in the upcoming Budget, is designed to assist first-time buyers by offering an equity loan of up to 20% on new-build properties. This initiative aims to lower the barrier to entry by allowing purchases with deposits as low as 2.5%. Eligibility is set with household income thresholds of £110,000, rising to £140,000 in London. The scheme is intended to mirror the success of previous programs like Help to Buy, which also utilized equity loans. However, the specifics regarding the duration of the interest-free period on these loans remain a point of concern for potential buyers, who fear that the eventual interest payments could negate initial savings and create a significant financial burden.
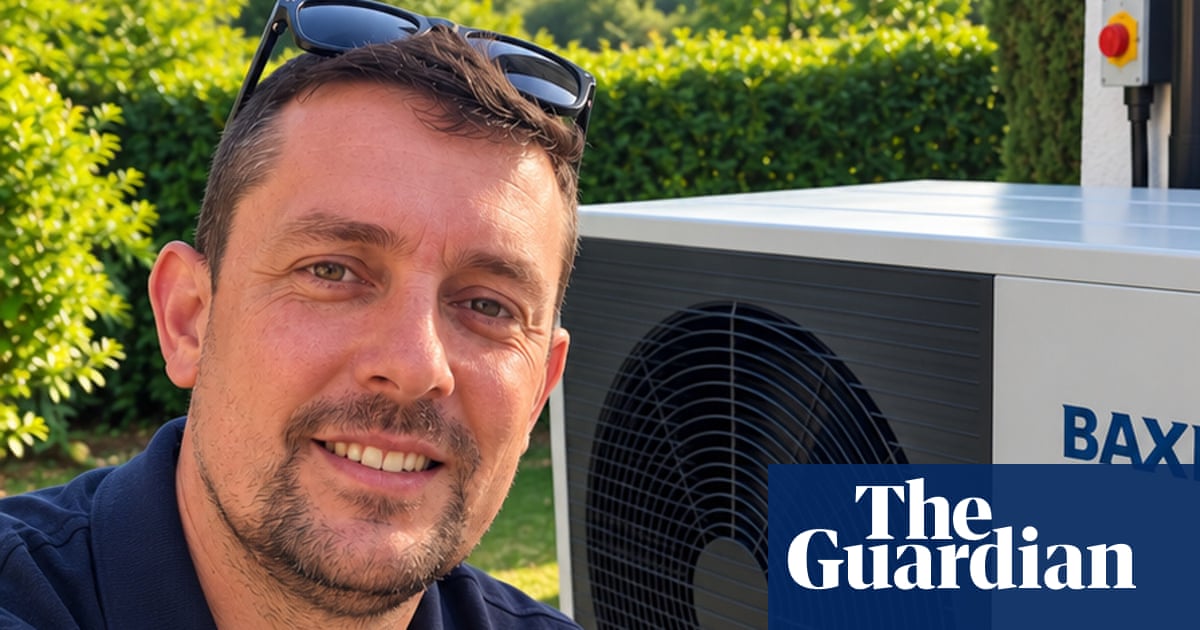
Luke Anstee
Luke Anstee, a 23-year-old IT professional, embodies the target demographic for such schemes, yet expresses significant reservations. Having moved frequently during his childhood due to his father's Army career, Anstee craves the stability of homeownership. Despite saving diligently for three years, he finds the current cost of living, including rising grocery and fuel prices, makes saving a considerable challenge. His concerns extend beyond the immediate deposit; he is wary of accumulating more debt, particularly the potential long-term costs associated with the government's equity loan. Anstee views the scheme as a potential gamble, dependent on future interest rate stability, and questions its long-term viability as a sound financial decision.
Julia Weston
Julia Weston, an experienced estate agent with over 30 years in the field, offers a professional perspective on the potential pitfalls of shared-equity schemes. She points out that rising interest rates could significantly increase the cost of these loans over time, especially when a buyer's initial mortgage deal expires. Weston highlights that shared-equity loans, similar to the previous Help to Buy program, require buyers to factor in not only their primary mortgage but also the repayment of the government's share, which can become substantially more expensive if interest rates climb. She also raises concerns about life events such as job loss, unexpected children, or a reduction in household income, which could make managing these combined financial obligations exceedingly difficult.
Key points
- A new government housing loan scheme aims to help first-time buyers with deposits as low as 2.5%.
- Potential buyers are concerned about the long-term financial implications of additional loans and rising interest rates.
- Rising costs of living, including groceries and fuel, are making it harder for young people to save for a deposit.
- Experienced professionals caution that shared-equity loans could become more expensive if interest rates increase.
- The scheme's success may depend on future economic stability and interest rate movements.
The scheme could successfully enable a generation struggling with high housing costs to achieve homeownership, providing much-needed stability and a chance to build equity. If interest rates remain manageable and the economy stabilizes, it could provide a crucial stepping stone onto the property ladder for many.
If interest rates rise significantly, the long-term cost of the equity loan could become prohibitive, trapping buyers in debt and potentially exacerbating affordability issues. The scheme might also inadvertently inflate house prices further, making it harder for those who don't qualify or choose not to use it.