French borrowing costs hit 24-year high as civil unrest and budget fears spook markets
France's borrowing costs have surged to a 24-year high, with the yield on 10-year government bonds exceeding 5%, driven by political instability, the government's failure to pass a budget, and widespread violent street protests.
Intelligence analysis by Gemini 2.5 Flash
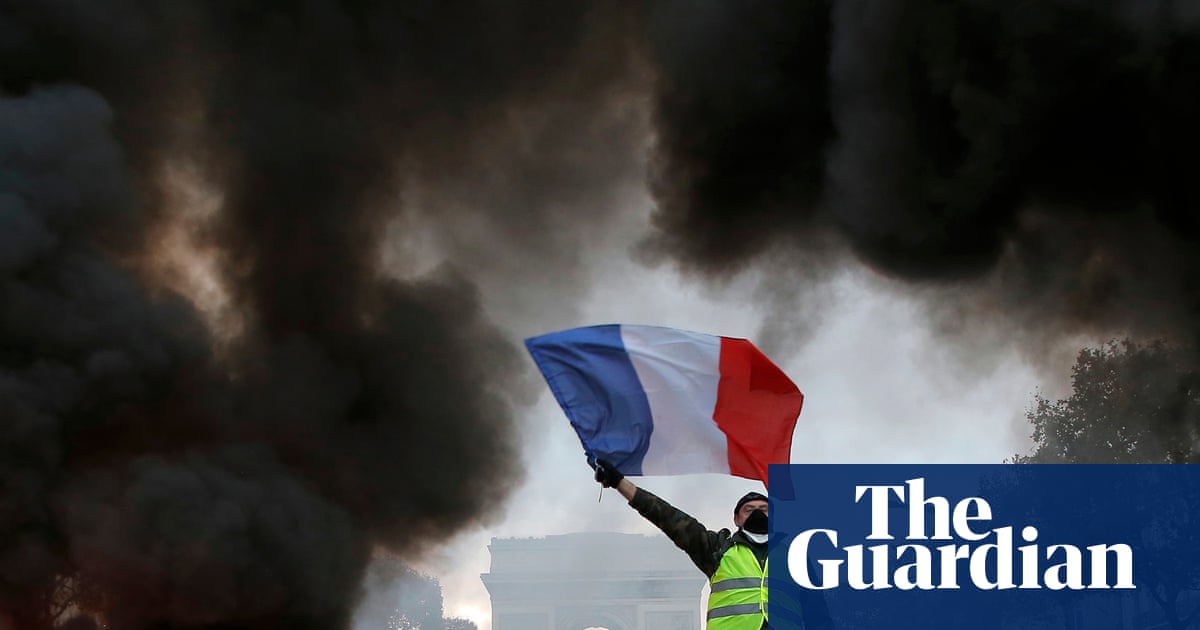
Financial markets are reacting negatively to France's escalating political and social turmoil, pushing up the cost for the government to borrow money. The inability to pass a budget, coupled with violent protests stemming from student grievances and cost-of-living concerns, has eroded investor confidence and weakened the euro.
Imagine your parents need to borrow money to fix the house, but they're arguing a lot and can't agree on how to spend it, and there are even some noisy protests outside. Banks might charge them more interest because they're worried they won't get their money back easily. That's kind of what's happening in France: the government is struggling to agree on its money plans, and there are big protests, making it more expensive for the country to borrow money to run things.
Analysis
The recent surge in French borrowing costs, with the 10-year government bond yield surpassing the critical 5% threshold, signals a profound loss of investor confidence in the nation's fiscal stability. This level, unseen in 24 years, reflects deep-seated concerns about France's ability to manage its finances amidst political paralysis and widespread social unrest. The higher yield means the French government must pay significantly more to service its substantial debt pile, which currently stands at 115.6% of GDP, exacerbating an already challenging budget deficit of 5.1% of GDP in 2025.
5%
The benchmark 10-year bond, known as an OAT, saw its yield climb above 5% in morning trading, a level not witnessed in nearly a quarter-century. This sharp increase in borrowing costs is a direct consequence of market apprehension regarding France's political stability and its government's fiscal discipline. Such elevated yields make it more expensive for the state to finance its operations and refinance existing debt, potentially diverting funds from public services or necessitating further austerity measures.
The sustained pressure on bond yields indicates that investors perceive a heightened risk of default or, at the very least, a prolonged period of fiscal mismanagement. This perception is fueled by the government's failure to pass its budget for the upcoming year, a critical piece of legislation that would outline its spending and revenue plans. Without a clear fiscal roadmap, the market remains uncertain about France's commitment to addressing its growing deficit and debt.
Emmanuel Macron
The political landscape under President Emmanuel Macron has been characterized by significant parliamentary gridlock since the snap election in 2024, where no single party secured overall control. This fragmented political environment has directly hampered the government's ability to enact crucial reforms, including plans to raise the pension age from 62 to 64 and implement measures to reduce state spending. The inability to push through these policies is seen by markets as a failure to address underlying structural economic issues.
Macron's government faces a dual challenge: navigating a divided parliament while simultaneously contending with increasingly violent street protests. These demonstrations, initially sparked by student demands for better school conditions, have broadened to encompass wider grievances over the rising cost of living. The aggressive police tactics employed to quell these protests have often escalated tensions, leading to riots, looting, and the destruction of civic property, further destabilizing the country and undermining investor confidence.
Japanese fund managers
International lenders have grown increasingly wary of France's financial health, with some, notably Japanese fund managers, withdrawing from lending to Paris altogether. This specific withdrawal by a significant segment of the global investment community underscores the severity of the market's concerns. The accusation of the French government becoming "fiscally incontinent" by these lenders highlights a perception of uncontrolled spending and a lack of commitment to fiscal responsibility.
For those lenders who remain, the price of extending credit to France has significantly increased, particularly for longer-period loans. This demand for a higher risk premium reflects the heightened uncertainty surrounding France's economic and political future. The erosion of confidence among international investors not only drives up borrowing costs but also has broader implications for the euro's value, as noted by Matthew Ryan of Ebury, who attributes the euro's underperformance to the persistent political risk premium in France.
Key points
- French 10-year government bond yields have risen above 5%, marking a 24-year high.
- The surge in borrowing costs is attributed to political concerns, the government's failure to pass a budget, and violent street protests.
- Protests, initially about school funding, have expanded to include cost-of-living issues and have led to riots and looting.
- Parliamentary gridlock since the 2024 snap election has blocked President Macron's reform plans, including pension age increases and spending cuts.
- France's budget deficit was 5.1% of GDP in 2025, with debt at 115.6% of GDP, both projected to worsen without remedial action.
- Some international lenders, including Japanese fund managers, have withdrawn from lending to France, while others demand higher interest rates.
The ongoing political gridlock and violent civil unrest in France could further deter international investors, leading to even higher borrowing costs and potentially a deeper economic downturn. Failure to pass a budget and address the deficit could trigger credit rating downgrades, exacerbating the country's fiscal challenges and weakening the euro further.